Insights | Multi-Purpose Urban Areas: Pulling Home Prices Back to Their Value as Homes?
25, August, 2026
Author: Tuan Pham
(Ngo & Partners is pleased to share the article "Multi-Purpose Urban Areas: Pulling Home Prices Back to Their Value as Homes?" by Tuan Pham, LL.M., Of Counsel at Ngo & Partners, originally published in Dan Tri News, 22 May 2026.)
A familiar paradox of Vietnam's real estate market: the more urban areas are built, the higher home prices climb — while the chance of owning a home slips further away for most people. For a segment of market participants, housing seems to have become an investment vehicle more than a place to live.
Against that backdrop, imagine an urban area in which half of all housing is welfare housing (social housing, resettlement housing and official-duty housing), while the other half is commercial housing sold at controlled, "appropriate" prices — where speculation is restrained and short-term flipping has almost no room left. Many would probably call the idea a touch of "science fiction".
Yet that story is gradually taking shape in Hanoi, through a draft scheme to build the "multi-purpose urban area" model now under the city's consideration. It is a very new scheme — indeed, the first of its kind in Vietnam.
In legal essence, the multi-purpose urban area is a special policy-piloting mechanism for the Capital, based on powers devolved from the central level under Resolution No. 258/2025/QH15 on piloting certain special mechanisms and policies for major, important projects in Hanoi, and under the Law on the Capital. Notably, although the model is called "multi-purpose" — because it houses multiple housing types and multiple urban functions — the whole design points towards one rather clear purpose: serving genuine housing needs.
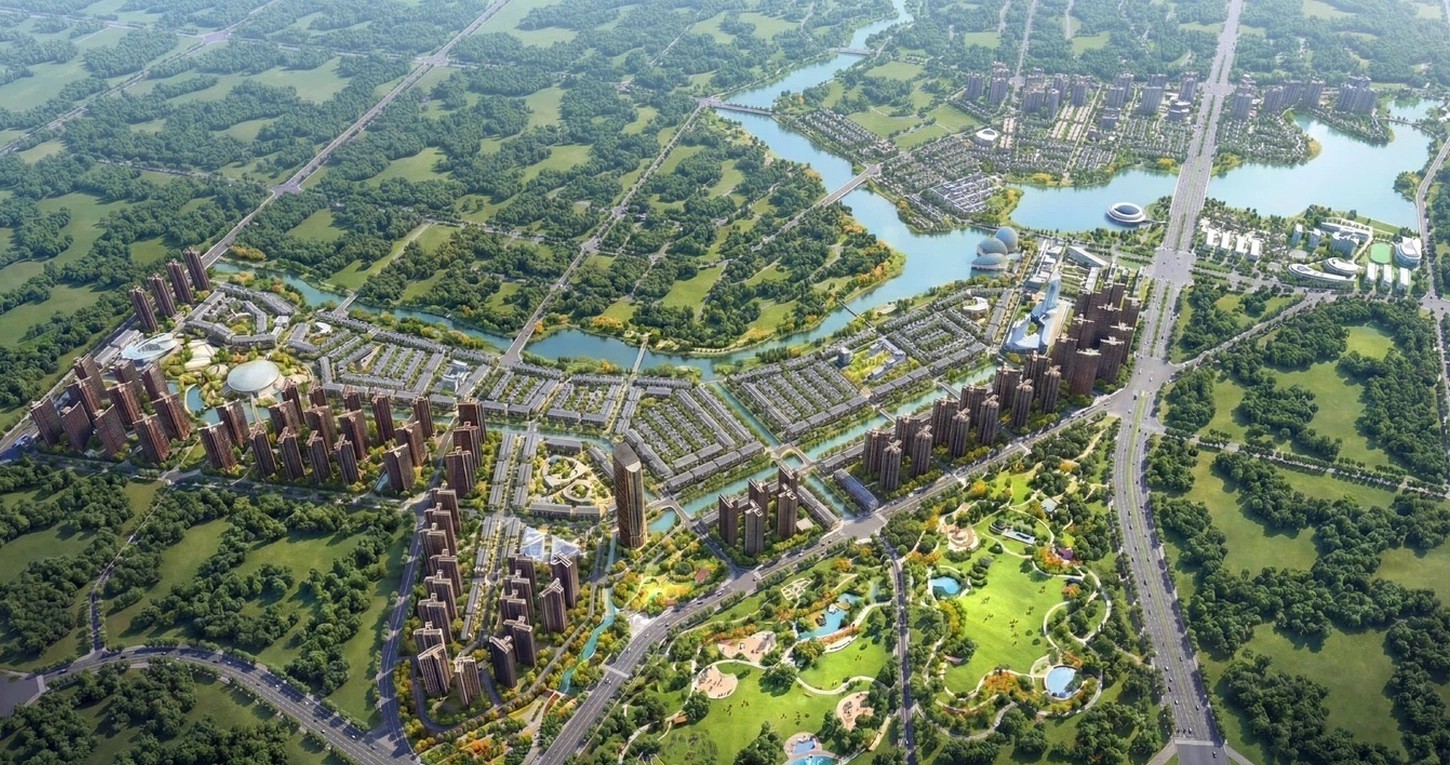
Under the direction the city is studying, multi-purpose urban areas would follow a compact, smart-city model — "live, work and enjoy amenities in place". Each urban area would have a minimum scale of around 150 hectares, planned comprehensively. Within the housing mix, welfare housing is expected to account for around 50–60%. The remainder would be affordable commercial housing.
From a legal and market perspective, this is a major shift in real estate development thinking. For many years, most urban area projects have run on market mechanisms, with social housing typically holding only a small share (20% of residential land area within a project). In the multi-purpose urban area, by contrast, welfare housing is placed at the centre.
The scheme's most striking feature lies in its control mechanism for commercial housing. Under the draft, the developer's profit on the commercial housing component is capped at 15% of the total construction investment cost of that component. All costs, revenues and pricing plans must be verified — even audited — by the authorities before going to market. In other words, commercial housing within a multi-purpose urban area would no longer operate entirely on the free-market mechanism as usual. In effect, the pilot takes real estate out of the logic of pure speculation.
It does not stop there. Buyers of commercial housing would be restricted from transferring for three years from full payment. Should they need to sell within that period, they may transfer only to the developer, at a price not exceeding the contract price. This is perhaps one of the firmest rules ever applied to commercial housing.
From a policy perspective, the Capital's thinking is very clear: restrain speculation, restrain flipping, and return the real estate market to its true nature — "homes are for living in". At a time when home prices are continually pushed up by short-term speculative activity, controlling profit and restricting transfers is one way to slow price growth and pull real estate closer to people's genuine need to settle.
A scheme this strong on welfare objectives, however, inevitably invites debate about market mechanisms.
Several important elements still need refinement. The scheme has not yet truly clarified the criteria for identifying "genuine occupants". Who will be entitled to buy commercial housing at appropriate prices? The question matters greatly, because it bears directly on the project's sales and economic viability.
There is also a certain tension between the welfare objective and market incentives. When a project faces capped profit, controlled selling prices, transfer restrictions and auditing across its entire life cycle, its appeal to investors will certainly fall relative to ordinary commercial projects.
Meanwhile, delivering an urban area of 150 hectares or more demands enormous capital, a long implementation horizon and exposure to considerable legal risk. The incentives in the new mechanism are not yet truly attractive enough. If the State wants developers in, it must offer sufficiently strong support "in exchange": cleared land funds, dedicated investment procedures, credit incentives, and legal stability throughout the life of the project.
Practice shows that in real estate, time all but determines a project's financial performance. If developers can obtain shortened procedures, less legal overlap, and faster planning, land allocation and investment approval, the economic value gained may far exceed a few extra percentage points of profit.
Because in real estate, "time is money".
In sum, the greatest challenge for the multi-purpose urban area lies not in how many apartments get built, but in designing a mechanism strong enough to counter speculation yet attractive enough for developers to invest. Achieve that, and this could mark a notable turn in Vietnam's housing development thinking — towards urban areas where the lights are switched on by residents, not by apartments waiting for prices to rise.